Summary: Do you hate having debt? Does the thought of going into debt to invest in real estate make you nervous or make you feel like you are going backwards financially? If this sounds like you, here’s why debt is a good thing when investing in real estate and how avoiding debt is likely hindering your journey to financial freedom!
We frequently encounter people who hate the idea of being in debt. From student loans to mortgage debt, their goal is to pay off all loans as quickly as possible. To them, getting rid of debt is a major milestone on their journey to financial freedom.
For many of these same people, the idea of going right back into debt in order to invest in real estate feels like they are going backward. So they choose to pay all cash, or aggressively pay down loans, on their investment properties in order to become debt-free again.
But what are the ramifications of this approach? Is it a good idea to have zero debt when you are investing in real estate? What if you are pursuing Fast FIRE? What is the best approach if your goal is to achieve financial freedom while you’re still young enough to enjoy it?
In this article, we compare and contrast debt-free real estate investing vs. investing using debt (also called leveraged investing). We also look at it through the lens of Fast FIRE, how your journey to Fast FIRE is affected if you choose not to take on any debt.
The situation
To make it interesting, we’ll use a case study to compare debt-free vs. leveraged investing.
Let’s just say we have a physician couple with $400,000 dollars to invest in real estate.
Now, this probably sounds like a ridiculous amount of money to all of you. And, for many of you starting out, it is a lot. But, for those of you who have been working for 5-10 years as attendings, this is not as crazy as it sounds.
I bet many of you have a similar amount of cash tied up right now among the equity in your primary residence, your retirement savings, and 529 college savings plans. It’s also not a crazy amount if you are considering liquidating your retirement accounts like we are.
So, stick with me, and let’s see what you can do with $400,000 debt-free vs. leveraged.
Debt-free real estate investing
Let’s take this money and buy $200,000 duplexes.
To keep things simple, let’s assume there are no closing costs or any repairs/renovations. We’ll also set the insurance, taxes, utility costs, vacancy, property management costs and gross rental income as the same for each duplex.
Because you aren’t taking on any debt, you’ll pay all cash for this duplex, and as a result, you can only buy two of them.
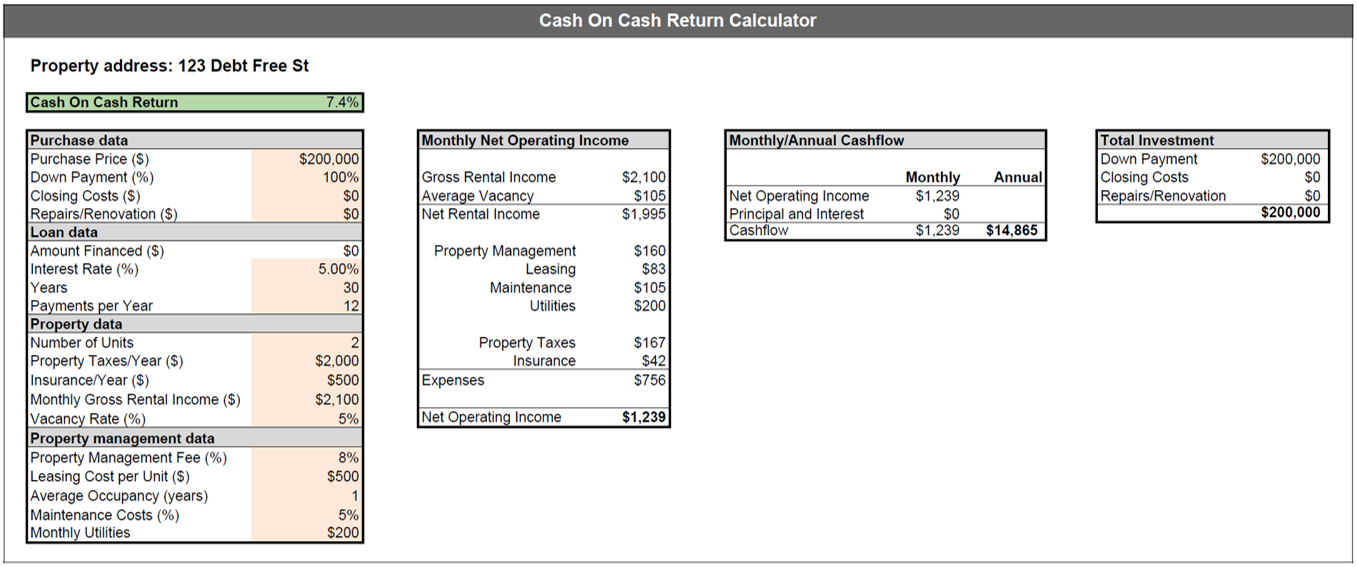
So in this example, each duplex will cash flow $14,865 for a cash-on-cash return of 7.4%.
In total, you’ll make $29,730 of cash flow per year from the two duplexes.
Leveraged real estate investing
This situation is considerably different when you’re using the bank’s money as leverage. For the sake of this example, let’s say you put down 25%. Now, because you’re using leverage, you can buy more properties. So instead of two duplexes, you can buy 8 duplexes or $1.6 million dollars worth of properties.
As in the debt-free example, we’ll assume there are no closing costs or any repairs/renovations.
We’ll also assume the expenses and income are the same.
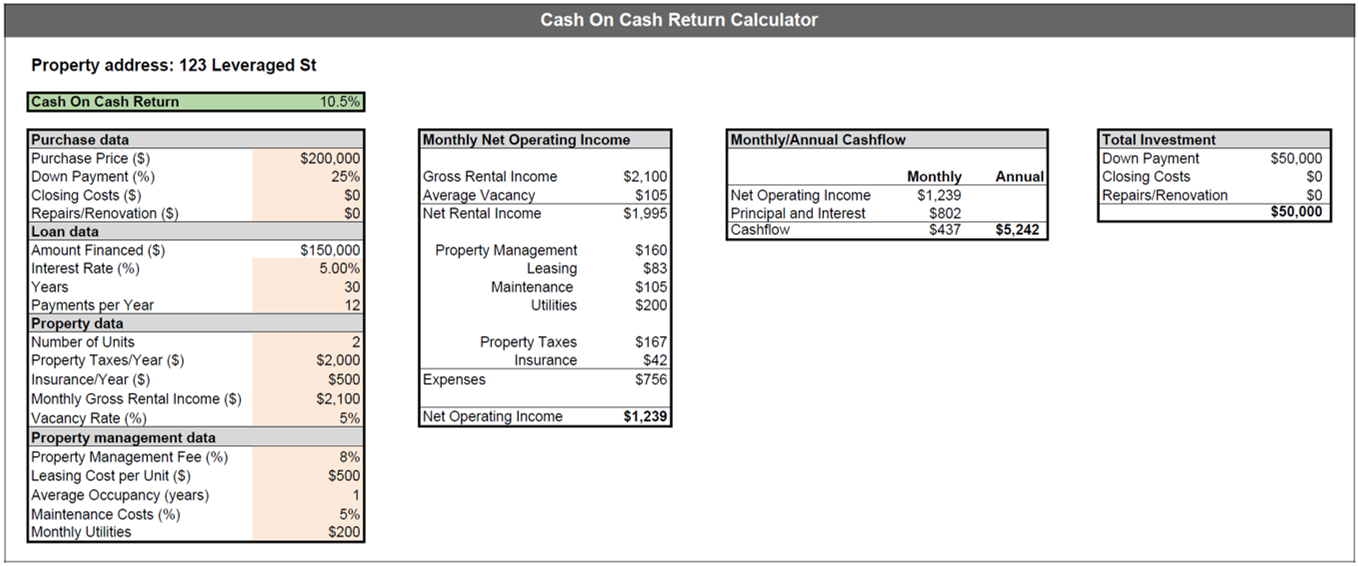
As you can see from the table below, your cash-on-cash return goes up from 7.4% to 10.5% when you use leverage. However, your cash flow goes down from $14,865 to $5,242 because you now have a mortgage payment.
But when you factor in the 8 duplexes you bought, your cash flow is $41,936 total per year compared to $29,730 in the debt-free example.
So, what are the upsides of being debt-free?
One upside of being debt-free is the improved ability to make it through downturns. Because you don’t have any mortgage payments, your cash flow is higher. Therefore, if you have two vacancies, you’re going to keep cash flowing through it.
This means you won’t have to come out of pocket to cover expenses. Hopefully, you’ll never be in a situation of struggling to make your mortgage payments and needing to foreclose.
Another upside of being debt-free is the emotional sense of well-being people get from not owing anyone any money. You know, if you lost your job tomorrow, you don’t have a lot of loans that you need to cover. You’ll just have less outflow per month.
Finally, there’s a simplicity to being debt-free. You don’t have to pay multiple bank mortgage payments each month. You don’t have to get multiple loans. You don’t have to quit-claim properties to LLCs (you can just buy them in LLCs!). This is all way less work.
What are the upsides of being leveraged?
As this example clearly shows, when you’re leveraged, you grow your real estate portfolio much faster. Instead of owning just two duplexes, you can own eight duplexes. Why is that important?
First, it’s important because you can gain real estate professional status much sooner. And that creates significant tax savings because now you can shelter your or your spouse’s clinical earnings. It’s much more likely to be able to justify the 750 hours of work required to be a real estate professional each year with eight duplexes than just two.
**For more information, be sure to download our free Quick Guide to Real Estate Professional Status to help you in your real estate investing journey!**
Second, you have your money spread throughout eight properties now, which lowers your risk.
Your risk is highest when you just have one or two rental properties. Then, one big disaster wipes out your whole portfolio. If you have eight though, your odds of an unfortunate incident wiping you out are extremely low.
Also, when you’re leveraged, the potential benefit of appreciation is much greater. Let’s say your portfolio appreciates 30%. Now you’re talking about $1.6 million x 30% = $480,000 in appreciation gained.
If you go the debt-free route, you’re only going gain $120,000 in appreciation ($400,000 x 30% = $120,000). By placing multiple bets, there’s a much larger upside.
You also have better tax benefits. Not only do you have the benefit of real estate professional status, you can do cost segregation/bonus depreciation on all of these properties.
Assuming you can cost segregate 20% of the total value of your properties, this means you could get $320,000 (20% x $1.6 million) in tax-write offs the FIRST YEAR! Yes, you read that correctly. If you’re normally paying at a 25% effective tax rate, that means you save $80,000 in taxes the first year.
In comparison, when you own just three properties in the debt-free example, your tax-write off the first year is $80,000 total (20% x $400,000), which is a $20,000 tax savings.
That’s ASSUMING you qualify for real estate professional tax status, which you may not since you only own two duplexes.
Let me just say that again…You are saving $80,000 in taxes vs. $20,000 by choosing to take on debt and be leveraged.
Put another way, you put in $400,000 of your money to buy leveraged real estate, and you got $80,000 back in tax breaks that first year.
Do you see why we are so passionate about the financial benefits of direct ownership of real estate?
Finally, the last benefit of being leveraged is that you’re less of a target for lawsuits. A paid off rental property is a sitting duck.
If one of your tenants sues the LLC that owns the property, that renter can take ownership of the property if they win the suit. If your property is leveraged, though, they get only the value left over after the mortgage is paid. That’s way less attractive than a fully paid off property.
Which is the right approach for you?
Only you can really answer this question.
It really comes down to balancing the level of stress you feel with having loans and whether not having that stress is worth losing the substantial financial benefits associated with being leveraged.
The right balance is different for each person.
To leverage or not to leverage…that is the question.